One of the most common questions we get: can I run Strike in my IRA or my Roth IRA?
Short answer: yes. And the rules don’t change much at all. Let me walk you through why, what to think about, and the one thing I can’t help you with.
Strike already plays by IRA-friendly rules
Here’s why it fits.
Retirement accounts have restrictions. In general, you can’t borrow money inside them, and a lot of complicated products are limited or off the table.
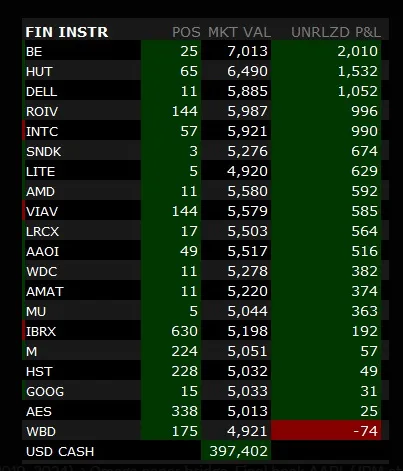
Strike already plays by those kinds of rules. It only buys regular U.S. stocks. No options, no futures, no crypto. It uses no leverage, so it doesn’t need to borrow anything. And the rules are exactly the same as in a regular account. Rank the stocks, hold the strongest 20, rotate monthly.
So you open an IRA at Interactive Brokers, in your name, and it runs the same way.
Want to see how the IRA setup works at Interactive Brokers?Book a call →Hear it from people who use Strike Monthly rotation means lots of trades
So why do so many people ask about this? Taxes.
Strike rotates every month. That means a lot of buying and selling. In a regular taxable account, those sales can create short-term gains, and you may owe taxes on them every year.
Inside an IRA or a Roth IRA, trades inside the account generally aren’t taxed each year. How and when you get taxed depends on the type of account and the rules for withdrawals.
Now, here’s the part I can’t help you with. I’m not a tax advisor, and Capital B28 doesn’t give tax advice. Whether an IRA or a Roth makes sense for you, contribution limits, rollovers, withdrawals, all of that is a question for your tax advisor or CPA. Please talk to them before you move retirement money anywhere.
Retirement money deserves extra care
Two more things before you decide.
First, we recommend at least 53 thousand dollars in the account. With 20 positions at roughly equal weight, you need enough money for each position to be a sensible size.
Second, remember the swings. Our deepest drawdown on the record is 37 percent. If you’re close to retirement and you need that money soon, a drop like that hits differently. Think hard about how much of your retirement money belongs in any single strategy, including this one.
Same rules. Your IRA. Your name.
So yes, you can run Strike in a traditional IRA or a Roth IRA. Regular stocks, no leverage, same rules, in your own account at Interactive Brokers. Talk to your tax advisor about the tax side, and keep the swings in mind.
If you want to see how the IRA setup works, go to strikealgo.net and book a call.
Why this matters if you’re considering Strike
Retirement money deserves extra care, and that’s exactly why Strike runs in an account you own, with no leverage and rules you can read. On a call we’ll walk through the IRA setup and help you think about how much belongs in any one strategy.
What happens on your call1We open the record togetherThe verified report, every month, the good and the bad. Ask anything.
2We map it to your accountHow Strike would run in your own Interactive Brokers account, the minimum, and what the swings could feel like.
3You decidePaper trade first if you like. No pressure, and if it isn’t a fit, we’ll tell you.
$100,000, same months
Jegadeesh & Titman 1993George & Hwang 2004Moskowitz, Ooi & Pedersen 2012
$100,000 invested April 2020, value September 30, 2026. MTUM NAV total returns per BlackRock. Strike: verified model record, gross of fees. Same months.
 Click to watch the video2:24 · Turn your sound on 🔊